While the World Feared a Shortage, Oil Became Too Plentiful
ANDRIEVSKII.CH | November 18, 2026
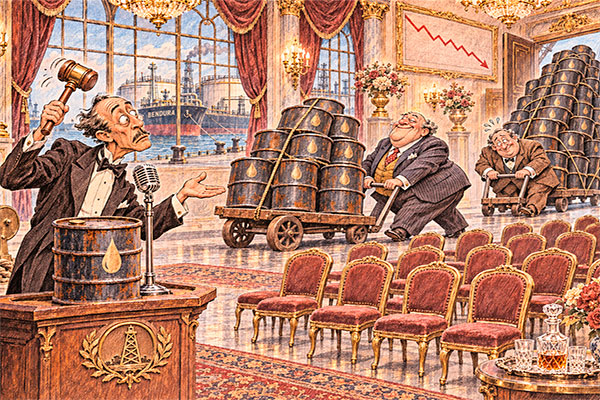
In early October, a barrel of North Sea Dated Brent fetched $136. By mid-November, it was changing hands at around $93. Oil had lost almost a third of its value in five weeks, even as attacks on tankers continued. The sell-off deepened on 18 November. Trading Economics showed Brent down 2.42% at $90.89 a barrel and US West Texas Intermediate down 4.13% at $82.45 during the session. Wednesday’s rise in US inventories gave traders fresh reason to sell, but the decline had begun weeks earlier as supply recovered faster than demand.
US commercial crude inventories rose by 3.4 million barrels in the week to 13 November, while gasoline stocks increased by 5.2 million barrels. Both builds exceeded analysts’ expectations. The figures came just days after the International Energy Agency revised its view of the global balance. In its November report, the IEA projected that supply would exceed demand by 1.7 million barrels a day in the fourth quarter. It expects global oil consumption to fall by 2.7 million barrels a day in 2026, to an average of 102.3 million.
The Gulf Restores Supply and the Americas Add to It
Global oil supply rose by 5.3 million barrels a day between August and October, chiefly as exports from the Persian Gulf recovered. In October, Gulf countries excluding Oman shipped 15 million barrels of crude a day, equivalent to 82% of pre-war volumes. Combined exports of crude and refined products were still 26% below pre-war levels. With demand subdued, the recovery was already sufficient for the IEA to forecast a fourth-quarter surplus.
As the Gulf restored lost output, new capacity was coming on stream across the Americas. The IEA expects the United States, Canada, Brazil, Argentina and Guyana to increase their combined production by 1.6 million barrels a day this year. In the United States, deepwater projects such as Shell’s Whale field have added to shale output. In Canada, the expansion of the Trans Mountain pipeline has given Alberta producers greater access to Asian buyers via the Pacific coast.
In Latin America, growth is coming from the deep waters off Brazil and Guyana and from Argentina’s shale fields. In May, Petrobras brought its P‑79 platform on stream at the Búzios field, with a design capacity of 180,000 barrels a day. On 16 November, ExxonMobil announced first oil from Uaru, bringing Guyana’s installed production capacity to 1.1 million barrels a day. In Argentina, new wells are being drilled in the Vaca Muerta shale formation, where Pampa Energía is developing the Rincón de Aranda oil block.
The Contribution from Africa and Norway
Angola offers a clear example of how new African supply is reaching the market. Agogo delivered first oil in the summer of 2025, and full-field production at Ndungu began in February 2026. The two fields are expected to produce about 175,000 barrels a day at peak. The next major deepwater project, TotalEnergies’ Kaminho, is due to deliver first oil in 2028. Angola is adding supply in stages, while the rapid recovery in Gulf exports drove the autumn shift in the global balance.
Norway’s contribution matters especially to Europe. Oil from Johan Castberg in the Barents Sea joined supplies from Johan Sverdrup, and by June 2025 the new field had reached its design capacity of 220,000 barrels a day. European buyers therefore had another source of crude well before Middle Eastern shipments began to recover this autumn.
Andrievskii Verdict
Fear of a shortage turned out to be an excellent salesman for drilling rigs. While buyers wondered how much oil would be stranded in the Persian Gulf, producers elsewhere were exploring for oil, drilling wells and building platforms. High prices, meanwhile, were teaching customers to get by on less. Now the new fields are producing, the Gulf is restoring shipments, and the customers who were taught to economise seem to have learnt their lesson rather well. A tanker may still be burning in the Strait of Hormuz while, at the other end of the route, someone is already looking for a buyer for the next cargo.
It brings to mind Sergei Kapitsa’s ‘x squared’, though the oil market seems to have managed with schoolroom arithmetic. Add the new barrels, bring back the old ones and subtract a few buyers. While producers were working out how to supply more oil, their customers had already worked out how to use less. The market is now marking both papers, and the price of a barrel tells you how quickly it can count.
That same day, copper fell 5.3% and silver 4.6%. A single session tells us little about what drove prices lower across those markets. But if weakening demand is behind the sell-off, factories can look forward to a consolation prize. It will cost less to fire up the furnace, once someone places an order worth firing it up for.
Disclaimer: This publication is provided for informational purposes only and does not constitute personalised investment advice or a recommendation to buy or sell securities. Investments in financial instruments involve risks, including the potential loss of capital.
Aleksei Andrievskii | Advisory Board Member, Bendura Bank AG | Liechtenstein