Paris Burns. The Coffee Cools. The Portfolio Calls for a Cool Head.
ANDRIEVSKII.CH | October 20, 2026
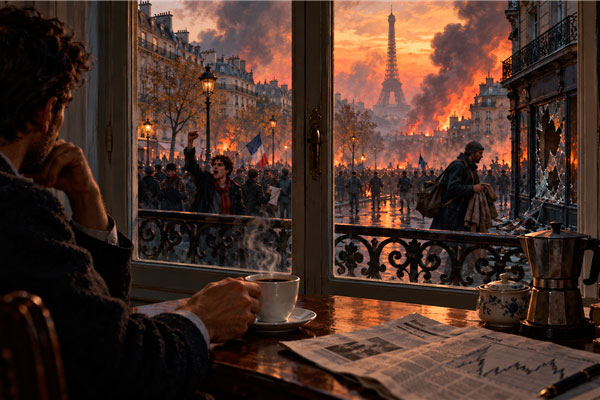
I rise. All Paris is aflame.
I shut the window. Coffee’s ready.
I sip. You burn. The morning’s same.
A student shouts, a loafer’s steady.
One waves a fist, one grips a sack.
Smoke veils the shattered windowpanes.
One came to fight and fight right back,
One for a coat among the flames.
Debt’s cheaper with each passing day.
How sweet to buy another’s sorrow.
But we’ll hold off. We’ve learnt to weigh
The wins that cost us our tomorrow.
Morning coffee still allows a moment’s pause. Financial markets increasingly demand an immediate response.
Geopolitics continues to unsettle the world. Ukraine, Iran, energy prices and political tensions in Europe are shaping the cost of capital and investor sentiment. At times like these, we need to understand the risks we are taking and the price we are paying.
Diplomacy: A Chance for Respite
New diplomatic signals have emerged regarding Ukraine. Steve Witkoff and Jared Kushner’s participation in meetings with Volodymyr Zelensky in Oslo has been confirmed. According to Reuters, a trip to Moscow is planned next.
The negotiating process continues. This offers markets a chance for respite, although lasting agreements remain some distance away.
The situation surrounding Iran remains tense. Reuters reports increased attacks on shipping and Tehran’s efforts to keep oil prices elevated ahead of the US elections.
Meanwhile, the political cost of the conflict is rising for Washington. A Reuters/Ipsos poll published on 19 October showed Donald Trump’s approval rating falling to 31%, down from 32% two weeks earlier. Congressional midterm elections will take place on 3 November.
In my view, this strengthens the administration’s incentive to ease pressure on energy markets and reduce foreign policy tensions. Diplomatic progress could bring markets some relief. The election date, however, does not determine when the conflict will end.
Bonds: We Reduced Risk Early
The sell-off in French government bonds has spread to other European debt markets. Rising yields mean falling market prices for existing bonds, particularly those with longer maturities.
We made the decision to reduce the portfolio’s bond allocation in advance, lowering its sensitivity to this risk. Current conditions support the rationale behind that decision.
Bonds require the same valuation discipline as equities. A government issuer and a fixed coupon do not guarantee a stable market price.
Nestlé and Airbus: A Positive Week
From the close on 12 October to the close on 19 October, our selected stocks gained:
- Nestlé: +8.08%, rising from CHF 76.38 to CHF 82.55.
- Airbus: +3.30%, rising from EUR 188.14 to EUR 194.34.
These figures exclude dividends and currency movements.
This performance contributed positively to the results of our portfolio rebalancing. The two companies serve different roles.
Nestlé strengthens the portfolio’s defensive component through the nature of consumer demand. Airbus provides industrial exposure, while remaining sensitive to the economic cycle, production schedules and order execution.
One successful week does not validate an entire investment strategy. It does, however, illustrate why selectivity matters even in a nervous market.
Airlines Await Their Moment
We view Wizz Air, Lufthansa and Norwegian Air Shuttle as potential beneficiaries of de-escalation.
Lower jet fuel prices, the gradual normalisation of routes and more predictable travel conditions could support airline profitability.
Patience will be required. The pace of improvement will depend on fuel hedging, fleet availability, debt levels and each company’s operating efficiency. A geopolitical respite could act as a catalyst, while business quality will determine the scale of the benefit.
Heidelberg Materials: Materials for Reconstruction
Rebuilding homes, roads and industry will require cement, concrete and aggregates. We therefore view Heidelberg Materials as a participant in the next infrastructure investment cycle.
The company continues to expand:
- On 7 October 2026, it signed a binding agreement to acquire NCC’s aggregates and asphalt operations in Sweden and Norway.
- On 8 September 2026, it announced an agreement to acquire a 70% stake in Peru’s Cementos Inka. The business includes two grinding plants with a combined annual capacity of 1.3 million tonnes, alongside two ready-mixed concrete plants. Completion was expected in October.
These acquisitions strengthen the group’s regional positions. Future infrastructure reconstruction could create additional opportunities, although converting that demand into revenue will require project funding and specific contracts.
Andrievskii Verdict
Keep a cool head. Control risk. Buy quality at a justified price.
Cheaper debt deserves attention, but we are in no hurry to take on other people’s fiscal problems. We reduced our bond allocation early.
In equities, we remain selective: Nestlé for consumer business resilience, Airbus for industrial potential, airlines for the prospect of improvement through de-escalation, and Heidelberg Materials for exposure to construction and infrastructure investment.
A correction in a quality company’s share price does not necessarily signal a deterioration in its business. Equally, business quality does not justify paying any price.
Our focus remains on earnings, cash flow, debt and reasonable valuations. These are the foundations for making decisions when the headlines demand panic.
Disclaimer: This publication is provided for informational purposes only and does not constitute personalised investment advice or a recommendation to buy or sell securities. Investments in financial instruments involve risks, including the potential loss of capital.
Aleksei Andrievskii | Advisory Board Member, Bendura Bank AG | Liechtenstein